3 Bedrooms | 2 Bathrooms | More Than 2,000 Sq. Ft. | Fenced Backyard | Optional Boating AccessPresented by Michael Downer, Broker Associate | Downing-Frye Realty | Quintessential NaplesMore Space,
Dated: October 20 2022
Views: 90
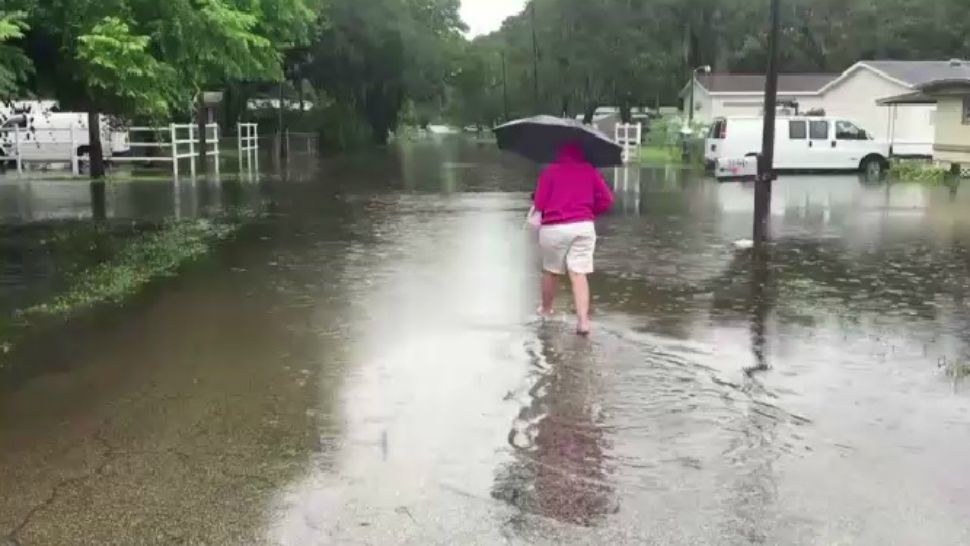
If you live in Southwest Florida, you understand rain. It seems like just about every day it rains here in the summer, which can lead to flooding. This blog may help you to understand lender-required flood insurance.
FEMA, (Flood Emergency Management Agency) conducts flood insurance studies throughout the U.S., with the cooperation of local officials, to identify high flood risks called SFHA (Special Flood Hazard Areas). These SFHA are areas within the floodplain that
have a 1% chance of being flooded in any given year. Over a 30 yr. period, the life of most residential mortgages, there is a 26% chance that a home within identified SFHA will be flooded.
National Flood Insurance Program Act of 1968 (NPIF) which U.S. Congress passed, authorizes them to provide an opportunity for property owners to purchase flood insurance protection made available by the federal government.
Homeowners who take out a mortgage from a lender that is federally regulated or insured, such as an FHA mortgage, and buy a home in a high-risk flood zone, also known as the SFHA, will be required to buy flood insurance. In most cases, the homeowner will have to pay for flood insurance every year until the mortgage is paid off.
Flood damage is not typically covered by a homeowner’s insurance policy. Flood insurance protects two types of insurable property: building and contents. The first covers your building; the other covers your possessions. Neither covers the land
they occupy.
The cost to insure a property against flood damage is determined by certain, factors such as the year of building construction, number of floors, level of flood risk, and the
amount of coverage required by the lender. This amount should be based on the cost to rebuild, which can be obtained from your homeowner’s insurance company.
You can find out about the flood risk of any property at FloodSmart.gov.or contact us regarding any property which interests you and we will help you locate updated
information about flood-prone areas. If the website says the property is in a high-risk area, flood insurance will likely be required. The final decision depends on flood insurance rate maps and an official flood zone hazard determination. You can see the maps yourself at FEMA.gov. You should also ask your lender about its flood insurance requirements.
The MikeDowner.com website is the most comprehensive online source for Southwest Florida real estate information and services. Whether you are looking for the latest sales, trends, or homes for sale in Collier, Lee, Charlotte, or Broward Counties in Florida, Mike Downer and Coldwell Banker Realty have it all at your fingertips. Browse information regarding short sales, foreclosures, new construction, investment property, land sales, or commercial locations throughout Southwest Florida at www.MikeDowner.com or call Mike at 239-722-6453. #homesforsale#realestate
Your Luxury REALTOR®, Trusted Advisor — Quintessential Naples Team at Downing-Frye Realty®Michael "Mike" Downer is the REALTOR® you want in your corner when buying or selling real es....
3 Bedrooms | 2 Bathrooms | More Than 2,000 Sq. Ft. | Fenced Backyard | Optional Boating AccessPresented by Michael Downer, Broker Associate | Downing-Frye Realty | Quintessential NaplesMore Space,
Newly Renovated | Impact Windows | New Appliances | Room for a Pool | No HOA | Golden Gate CityPresented by Michael Downer, Broker Associate | Downing-Frye Realty | Quintessential NaplesLess Fixing.
4 Bedrooms | 2 Bathrooms | Lakefront Pool Home | Reflection Lakes Presented by Mike Downer, Broker Associate | Downing-Frye Realty | Quintessential NaplesA Little More Time to Enjoy FloridaSome
2 Bedrooms | 2 Bathrooms | First-Floor Residence | Bonita SpringsPresented by Mike Downer, Broker Associate | Downing-Frye Realty | Quintessential NaplesA Simple Way to Enjoy Southwest
 All information regarding a property for sale, rental or financing, school information and public tax records is from sources deemed reliable; PROVIDED, HOWEVER, that representations and warranties are not made about the accuracy thereof, and such information is subject to errors, omissions, updates, modifications, changes of price, rent rates, commissions, prior sales, leases or financing, changes in school boundaries, or withdrawal without notice. All information displayed on this Website should
be independently verified if any person intends to engage in a transaction based upon such information.
Show More...
 © 2026 Florida Gulf Coast MLS (FGCMLS) Information deemed reliable, but not guaranteed. The IDX data relating to real estate for sale on this web site comes in part from the Florida Gulf Coast Multiple Listing Service. The information being provided is for consumers' personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. Information is deemed reliable but not guaranteed.
 This data is up-to-date as of September 26, 2026 6:56 PM UTC Some properties that appear for sale on this website may subsequently have sold and may no longer be available. For the most current information, contact Downing-Frye Realty.
The information provided is for consumers' personal, non-commercial use and may not be used for any other purpose. The data relating to real estate for sale on this website comes in part from the Broker Reciprocity Program (BR Program) of M.L.S. of Naples, Inc.,
Florida Gulf Coast MLS, Marco Multi-List, Inc., My Florida Regional MLS, or Miami Association of Realtors. Properties listed with brokerage firms other than Downing-Frye Realty are marked with the BR Program Icon or the BR House Icon and detailed information about them includes the name of the listing brokers. The properties displayed may not be all the properties available through the BR Program. The data provided by the Broker Reciprocity Program, and the Information is Deemed Reliable But Not Guaranteed. The source of the information about real property available for sale or rent is the copyrighted and proprietary database of the M.L.S. of Naples, Inc., Florida Gulf Coast MLS, Marco Multi-List, Inc., My Florida Regional MLS, or Miami Association of Realtors. Copyright 2026 M.L.S. of Naples, Inc., Florida Gulf Coast MLS, Marco Multi-List, Inc., My Florida Regional MLS, Miami Association of Realtors.; all rights reserved.
Show More...
